Legendary investor Stanley Druckenmiller, renowned for his astute market insights, has executed a significant strategic shift within his artificial intelligence (AI) portfolio. After an early, highly profitable, but self-admittedly premature exit from Nvidia (NVDA) in 2024, Druckenmiller's Duquesne Family Office has rebalanced its AI holdings with a notable pivot.
In the most recent quarter, Druckenmiller completely exited his position in the AI chip stock Broadcom (AVGO). Concurrently, he initiated relatively large stakes in two other formidable AI players, moving further down the AI compute supply chain: Amazon (AMZN) and Alphabet (GOOG, GOOGL).
This bold move underscores Druckenmiller's approach to identifying investment opportunities borne from major shifts in the global economy and markets, with AI being a prime example. While valuation is often a secondary concern for him, it's worth noting that Broadcom's P/E ratio had surged to 40 at one point last quarter, a considerable jump from its sub-30 P/E when he initially invested.
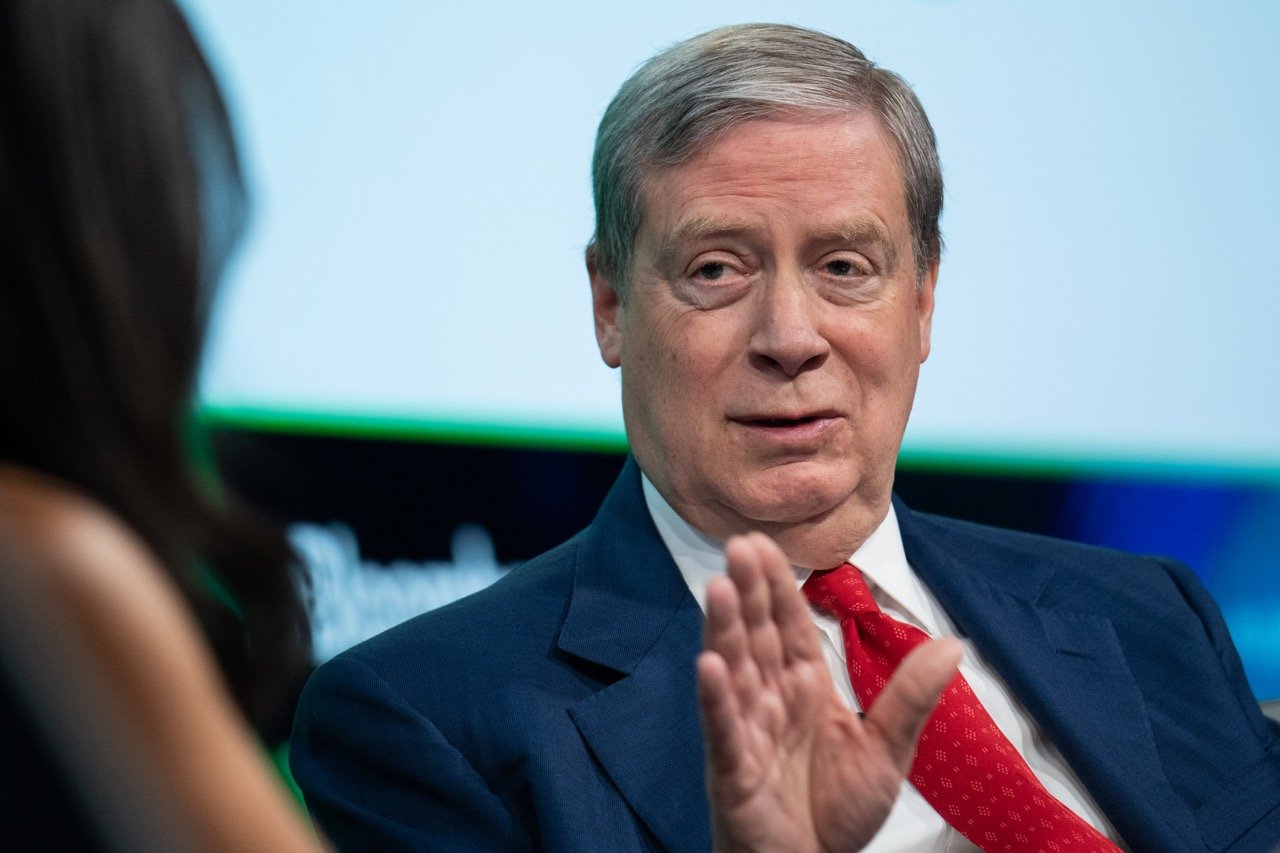
Stanley Druckenmiller, Duquesne Family Office chairman. Image source: Getty Images.
Druckenmiller's decision to favor hyperscalers like Amazon and Alphabet likely stems from their increasing control over their own AI infrastructure. These tech titans are pouring capital into new data centers, raising funds through debt and stock issuance, and developing custom silicon to meet the burgeoning demand for AI compute.
While Broadcom manufactures crucial networking chips and custom AI accelerators, including Alphabet's Tensor Processing Units (TPUs), the landscape is evolving. Amazon CEO Andy Jassy highlighted that the majority of new chips deployed in their data centers this year will be their proprietary Trainium chips. Alphabet, while continuing its partnership with Broadcom for TPUs, has also diversified by securing a deal with Marvell for specialized inference TPUs.
This trend suggests that major customers are exerting more influence over their chip choices. The long-term advantage appears to lie with companies that can dictate chip design and sourcing. Hyperscalers, with their comprehensive control over the AI compute supply chain, are increasingly seen as the ultimate beneficiaries.
Even for investors who are more valuation-conscious than Druckenmiller, Amazon and Alphabet currently present compelling opportunities. Amazon stock trades at approximately 20.5 times forward earnings expectations, while Alphabet is at just 16.4 times. These modest multiples are partly due to investor apprehension regarding both companies' substantial capital expenditures, which have temporarily led to negative free cash flow.
However, both companies boast immense backlogs of contracted revenue, with Alphabet reporting $514 billion and Amazon $496 billion in remaining performance obligations. This provides significant foresight into future demand and the expected returns on their substantial investments. As new data centers come online and chip utilization rates remain high, Amazon and Alphabet are well-positioned to convert these investments into strong operating results and attractive long-term returns for shareholders.