


Apple’s stock is showing resilience with nine consecutive earnings beats, driven by strong performance in iPhone, Mac, and Services. The new Siri AI is positioned as a key growth catalyst, potentially driving device upgrades and service subscriptions.
Despite a premium valuation compared to peers like Microsoft and Alphabet, Apple maintains a strong buy rating, with a 12-month price target of $398.25. However, challenges such as rising memory costs and regulatory hurdles for AI deployment could temper future growth.
Apple's Siri AI: The Next Frontier Poised to Redefine Stock Trajectory
Apple (AAPL) has once again surpassed earnings expectations, with its innovative Siri AI at the epicenter of a strategic battle. While surging services growth fuels optimism, mounting memory costs present a significant challenge, potentially driving the stock in opposing directions.

Price Targets desk. Editor: Vandita Jadeja.
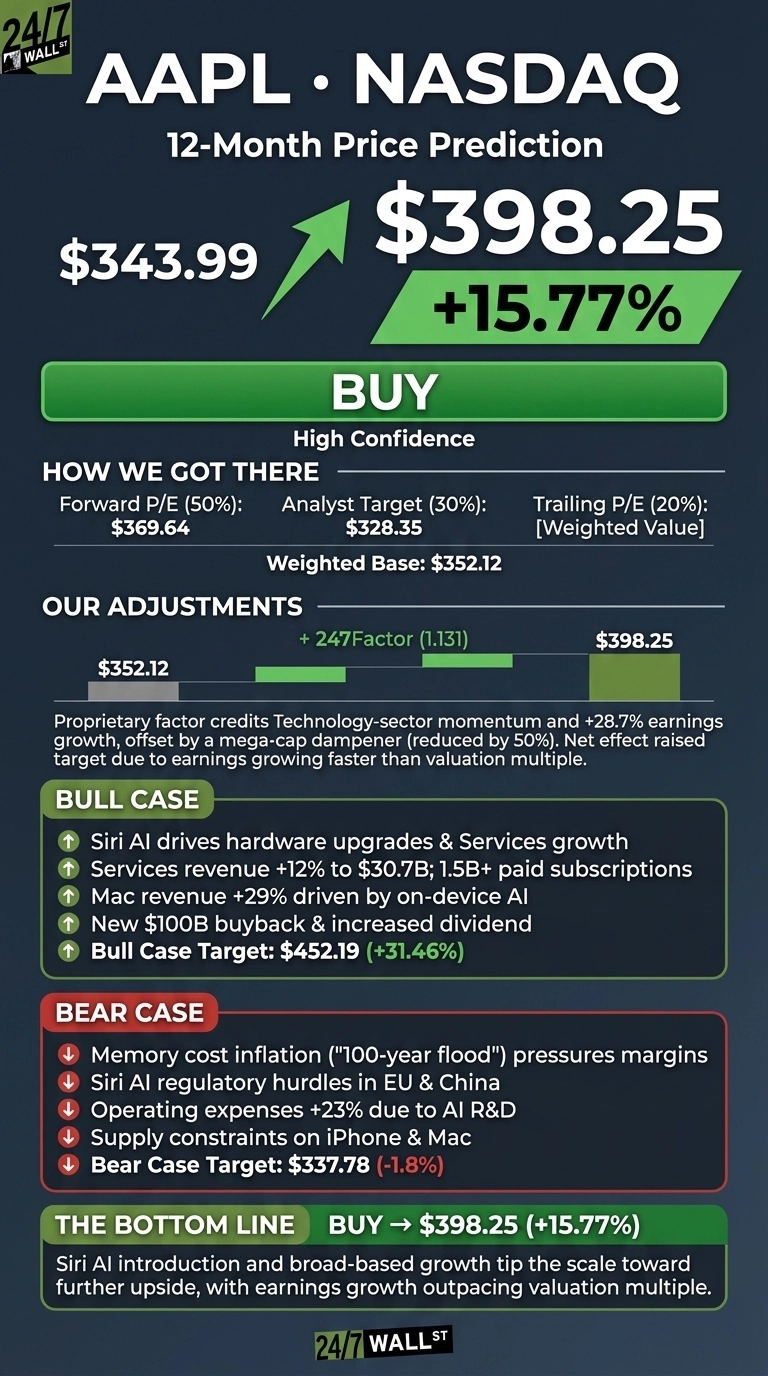
The 24/7 Wall St. price target for Apple (NASDAQ:AAPL) is set at $398.25 over the next 12 months, indicating a potential 15.77% upside from its October 21 closing price of $343.99. Shares were trading at $345.36 late Tuesday morning. Our recommendation remains a strong BUY with high model confidence.
| Metric | Value |
|---|---|
| Current Price | $345.36 |
| Price Target (24/7 Wall St.) | $398.25 |
| Potential Upside | 15.77% |
| Recommendation | BUY |
| Confidence Level | 90% |
Our high confidence stems from Apple's broad-based growth. Last quarter, iPhone, Mac, and Services all experienced double-digit growth. The newly launched Siri AI is poised to incentivize upgrades across Apple's massive installed base of over 2.5 billion active devices and drive further service subscriptions.
Nine Straight Earnings Beats Fuel Apple's Ascent
Apple has demonstrated remarkable resilience, with its stock up 27.39% year-to-date and 31.92% over the past year. Shares are currently trading just below their 52-week high of $348.15, significantly outperforming the low of $242.76.
In fiscal Q3, Apple reported impressive revenue of $109.42 billion, a 16.4% year-over-year increase. Earnings per share (EPS) reached $2.02, exceeding the $1.89 estimate, marking the company's ninth consecutive EPS beat. Bloomberg recently highlighted Apple as a favored AI hedge among investors due to its strong cash flow.
Reports indicate a short supply for the iPhone Duo, and John Ternus has taken the lead for future earnings calls, succeeding Tim Cook.
Bulls Eyeing Over $450 Driven by Siri AI's Potential
CEO Tim Cook described the reimagined Siri AI as "profoundly capable, deeply personal, and integrated seamlessly across our platforms." Apple is strategically positioned to monetize this advancement through iCloud+ upgrades and other service enhancements.
Services revenue soared to $30.7 billion, a 12% increase, supported by over 1.5 billion paid subscriptions. Mac revenue surged 29%, driven by demand for on-device AI processing. A new $100 billion share buyback program and a dividend increase to $0.27 further bolster investor confidence.
Analyst sentiment remains overwhelmingly positive, with 6 Strong Buy and 19 Buy ratings. The most optimistic bull case targets $452.19, representing a substantial 31.46% gain.
Headwinds: Memory Costs and Supply Constraints Loom
CEO Tim Cook described the current memory pricing environment as a "100-year flood," forcing Apple to implement price adjustments. The projected September-quarter gross margin of 47%-48% incorporates one-time tariff refunds that added approximately 2 percentage points to the margin and $0.11 to EPS last quarter.
Regulatory scrutiny for Siri AI's launch in the EU and China is ongoing. Furthermore, a cautious outlook is reflected in 6 analysts rating the stock as Sell or Strong Sell.
Operating expenses have risen by 23% due to increased R&D investment in AI. Cook also noted that supply constraints are primarily a "demand forecast issue." The bear case scenario suggests a potential downside to $337.78, a modest 1.8% decrease.
Apple's Valuation: A Premium Play Among Tech Giants
| Company | P/E Ratio | FCF Yield | Net Margin |
|---|---|---|---|
| Apple (AAPL) | 45x | 1.97% | 26.9% |
| Microsoft (MSFT) | 30x | 1.69% | 40.3% |
| Alphabet (GOOGL) | 15x | 1.76% | 32.8% |
When compared to its tech peers, Apple's valuation is the highest. Microsoft (MSFT) reported a 43% growth in its Azure business, though Q4 free cash flow declined by 23.19% amid a 109.63% rise in capital expenditures. Alphabet (GOOGL), a direct competitor, faces challenges with its Gemini AI and reported negative free cash flow of $5.855 billion in Q2, leading to a suspension of its buyback program.
Despite its premium valuation, Apple remains the only company among these giants consistently funding AI development while maintaining shareholder returns through buybacks and dividends. Considering these factors, the 24/7 Wall St. price target of $398.25 appears reasonable.
The Verdict: Siri AI Tipping the Scales Toward Apple's Upside
Our 12-month price target for Apple remains $398.25, supported by a BUY rating and high confidence. The core thesis rests on earnings growth continuing to outpace the company's valuation multiple.
The outlook brightens significantly if Siri AI proves to be a catalyst for increased iPhone upgrades and iCloud+ subscriptions. Conversely, persistent memory cost pressures impacting gross margins could dampen performance. On balance, our analysis indicates a continued upward trajectory for Apple stock.
Looking ahead, our model projects Apple's stock performance based on sustained growth trends:
| Year | Projected Price Target (24/7 Wall St.) |
|---|---|
| 2026 (Dec.) | $349.65 |
| 2027 (Oct.) | $397.25 |
| 2028 (Oct.) | $443.95 |
| 2029 (Oct.) | $491.53 |
| 2030 (Oct.) | $523.62 |
These projections assume Apple's continued strategic execution. A highly successful Siri AI launch could propel the stock towards $625.31 by 2030, while sustained margin pressures might cap growth closer to $367.52.






