




Anticipation is building for Alphabet’s third-quarter earnings report, expected to be a significant catalyst for investors. With the company strategically positioned to dominate the AI landscape, a robust performance from its Google Cloud division and new revenue streams from Tensor Processing Unit (TPU) sales are poised to propel its stock. Despite recent dips, its attractive valuation further strengthens the case for a post-October 28 rally.
An eagerly awaited event for Alphabet (GOOG -1.68%) (GOOGL -1.74%) shareholders is fast approaching: its third-quarter earnings announcement. The company appears exceptionally well-prepared for this report, and a combination of strong factors could send its shares soaring immediately afterward. Few companies are as strategically placed as Alphabet to thrive in the escalating AI 'arms race,' and with the stock currently more than 10% below its historical peak, this moment presents an opportune buying window.
Image source: The Motley Fool.
Alphabet's Strategic AI Investments Will Be Under Scrutiny
Artificial Intelligence (AI) is influencing Alphabet's operations in profound ways. A substantial portion of Alphabet's revenue comes from advertising across its Google suite of products, and with deep AI integration into these offerings, its business model has subtly evolved. Last quarter, Google Search revenue demonstrated a commendable 17% year-over-year increase, an impressive feat for such a mature business segment.
However, much of the attention will likely be on the performance of its Google Cloud division. As Alphabet's dedicated cloud computing business unit, Google Cloud delivered stellar results in Q2, with revenue surging an outstanding 82% year over year and its operating margin reaching 36%. Such robust growth is increasingly becoming an expectation. Looking ahead to 2026, Alphabet projects capital expenditures of approximately $200 billion, with the vast majority of this substantial investment earmarked for data centers.

NASDAQ: GOOG
Key Data Points
Investors will be keen to see a strong return on the significant capital being deployed. If Google Cloud can push towards a triple-digit growth rate, these massive investments would appear well-justified. This outcome is highly probable, with additional factors contributing to its upward trajectory.
Alphabet has innovated a cutting-edge AI computing chip, known as a Tensor Processing Unit (TPU), specifically engineered for demanding AI workloads. Initially designed for Alphabet's internal use, these units are now being offered to external clients, establishing a promising new revenue stream. Alphabet previously informed investors that TPU sales would gradually increase through 2026, with the majority of revenue expected to materialize in 2027. Nevertheless, investors are eager for clearer insights into this progression, and the upcoming October 28 earnings call should provide that clarity.
All these elements collectively suggest that Alphabet is poised to deliver exceptional financial results, a sentiment echoed by Wall Street analysts who anticipate a robust 25% growth rate—an impressive figure for a tech giant of this scale. This strong outlook, combined with its favorable valuation, positions the stock for a significant ascent following the earnings announcement.
Alphabet's Attractive Valuation Provides Upside Potential
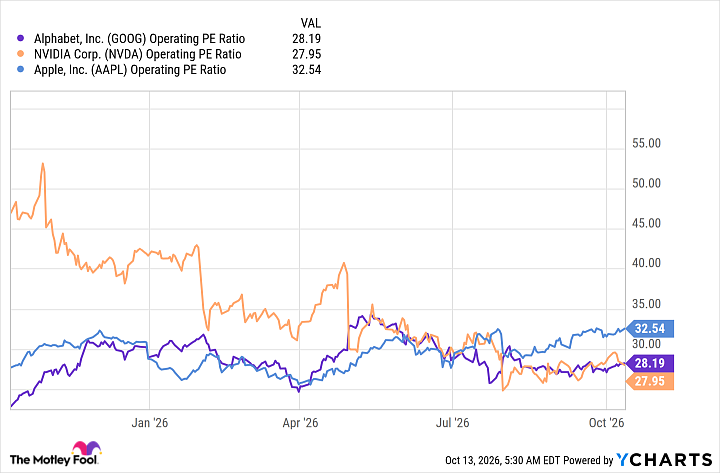
Many companies in the AI sector trade at elevated valuations, necessitating continuous, spectacular quarterly reports to avoid investor sell-offs. Alphabet, however, stands apart with a more reasonable valuation. While traditional earnings-per-share (EPS) metrics can be misleading due to significant gains in its investments over the past year (even if unrealized), rendering the price-to-earnings (P/E) ratio less effective, focusing on operating income provides a clearer picture.
GOOG Operating PE Ratio data by YCharts
Currently, Alphabet is valued at 28 times its operating income, aligning it with its $4 trillion market capitalization peers. This valuation is deemed quite reasonable and not significantly more expensive than its average over the past year, indicating that its stock gains are fundamentally driven by its results. Should this trend persist and Alphabet announce strong earnings, the stock is primed for rapid appreciation. All signs point to another stellar quarter for Alphabet, which could provide the necessary impetus for the stock to surpass its previous all-time highs and continue its upward trajectory.
Consequently, I believe Alphabet represents a compelling investment opportunity right now.