Marvell Technology is experiencing a surge in analyst confidence following a significant custom chip deal with Google, which includes a potential $12 billion equity stake. This strategic partnership, alongside continued involvement in Amazon’s Trainium chips, positions Marvell as a key player in the AI infrastructure buildout. The company recently reported record revenue and raised its fiscal year outlook, with analysts largely maintaining positive ratings and price targets, reflecting strong growth expectations.

Marvell Technology (MRVL) is capturing the attention of Wall Street, with analysts like Henry Huang from GF Securities highlighting its pivotal role in the custom AI chip market. Huang's positive outlook is largely fueled by Marvell's deepening ties with Alphabet's Google (GOOG) (GOOGL), projecting that three Marvell chip lines for Google could generate approximately $3 billion each by 2028. Furthermore, Marvell is expected to play an increasingly significant role in Amazon.com's (AMZN) Trainium chips, with revenue estimated at $1 billion this year and $2 billion next year. This wave of positive sentiment is echoed by multiple financial institutions, including Wells Fargo, Morgan Stanley, Susquehanna, and Rosenblatt Securities, all of whom recently raised their price targets for Marvell.
This surge in analyst confidence follows a landmark custom chip deal with Google, which includes a potential $12 billion equity stake in Marvell. This strategic partnership is anticipated to enhance Marvell's prospects for securing more of Google's future chip business. The article also addresses concerns regarding Marvell's involvement with Amazon's Trainium chips. While Marvell had previously lost design work for the next generation of these chips to a competitor, GF Securities' analysis suggests Marvell will continue to contribute to Trainium 3 and strengthen its position with the subsequent generation, particularly following the Celestial AI deal. The projected billions in Trainium revenue underscore that this is far from a complete customer loss.
The Milestone That Changes Marvell’s Story
The recent agreement with Google marks a significant turning point for Marvell, positioning it as the sole custom AI chip designer for all three major U.S. cloud providers: Amazon, Microsoft (MSFT), and Google. This achievement sets Marvell apart from competitors and potentially shifts its market perception from a clear number two to Broadcom in this sector.
The Google partnership is particularly reassuring for investors, as Google's commitment extends beyond a typical supply agreement, with share purchases tied to volumes through 2033. This equity stake signifies Marvell's critical importance to Google's long-term strategic plans. For a stock that had previously faced pressure on valuation rather than fundamentals, this level of customer validation serves to rebuild investor confidence.
About Marvell Technology Stock
Marvell Technology specializes in semiconductor solutions for data infrastructure, serving key markets such as data centers, cloud computing, artificial intelligence, telecommunications, and enterprise storage. Its products are essential for high-speed data transfer within data centers and communication networks, making them vital for AI workloads, cloud services, and internet infrastructure. Founded in 1995 and headquartered in Wilmington, Delaware, Marvell serves a global customer base through direct sales and distributors.
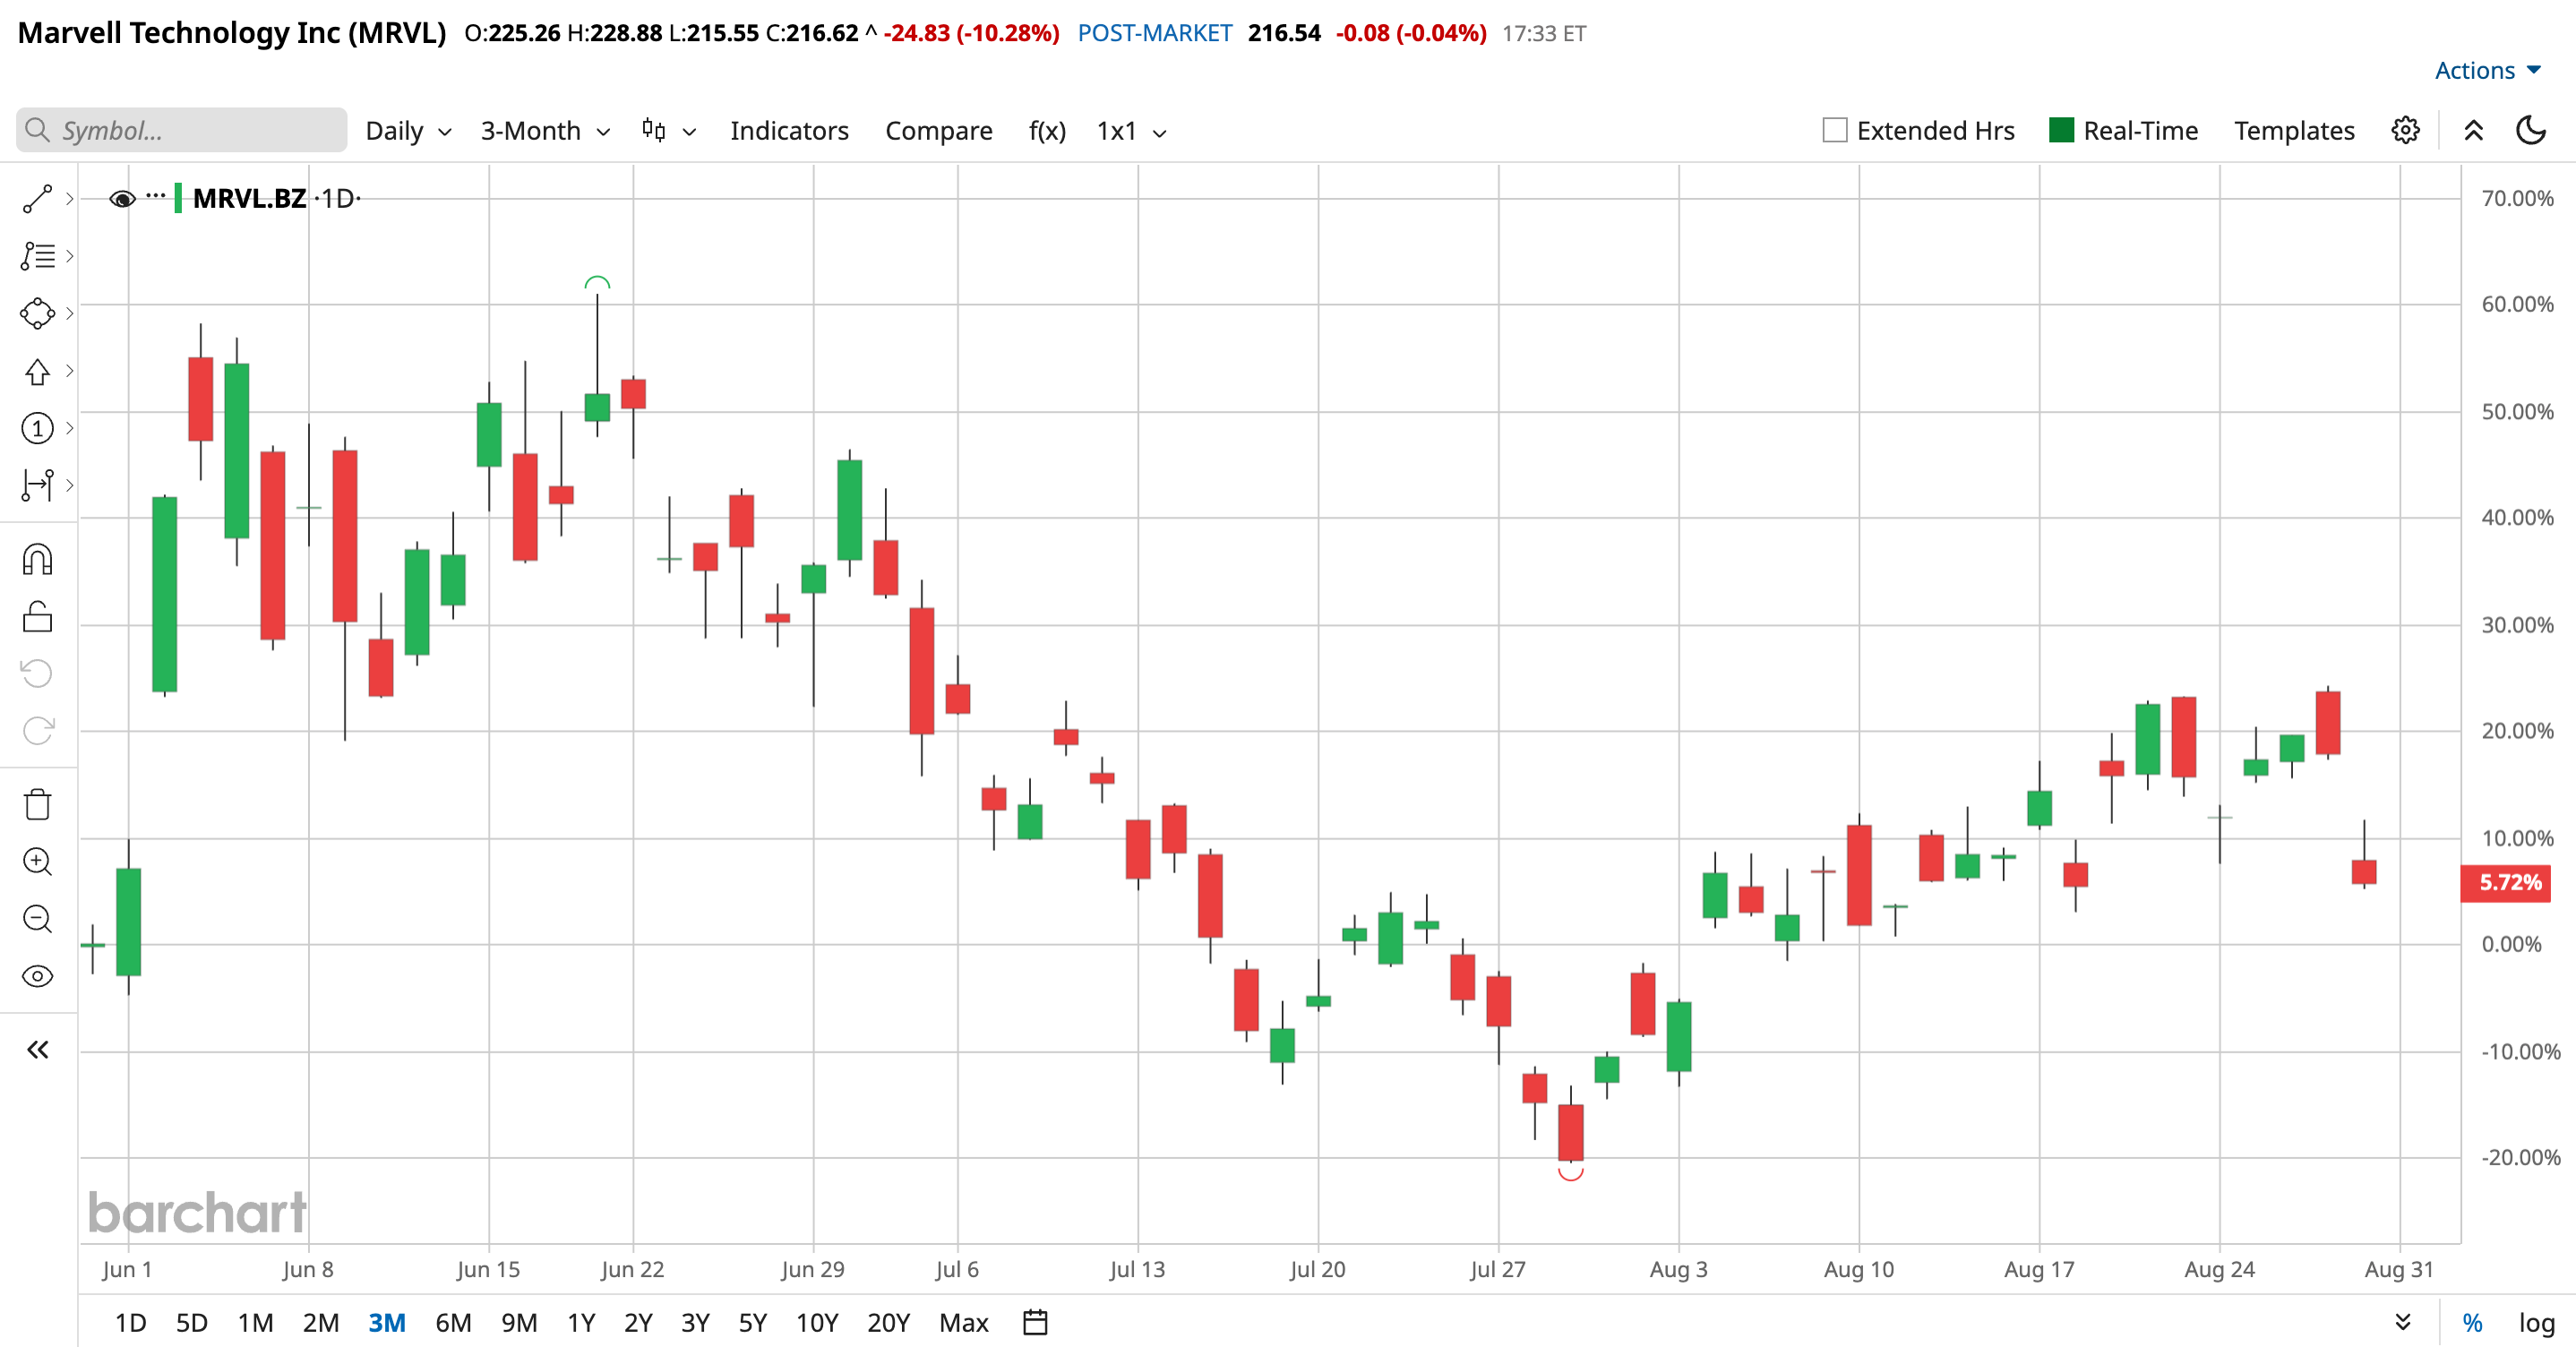
Over the past 12 months, Marvell has significantly outperformed the semiconductor sector, with its stock climbing an impressive 180.5%, far exceeding the iShares Semiconductor ETF's (SOXX) 101.4% gain. This strong performance has continued into the current year, with the stock up 154.9% against the sector's 68.9% rise.
Marvell's current valuation reflects high investor expectations for future growth. The forward GAAP price-to-earnings ratio stands at 127.68, which is substantial, though the company has only recently achieved consistent profitability. The forward price-to-sales ratio of 18.29 is 81.3% above its 5-year average, indicating a significant premium. However, the projected EPS growth—43% in 2027, 55% in 2028, 51% in 2029, and 46% in 2030—justifies this premium for a company of its scale.
The company maintains a robust balance sheet, with $3.84 billion in cash against $5.28 billion in debt, resulting in manageable net debt. This strong financial position, combined with its critical role in the AI infrastructure buildout, supports its current valuation and growth trajectory.
Marvell Sees Accelerating Growth as Data Center Business Expands
In its second-quarter fiscal 2027 earnings report released on August 27, Marvell announced record revenue of $2.74 billion, marking a 37% year-over-year increase. Earnings per share came in at $0.94, slightly exceeding the Wall Street consensus of $0.93. The non-GAAP gross margin was 58.9%, with a GAAP gross margin of 53.1%. The data center business experienced accelerated demand, driven by AI infrastructure spending, optical networking, and custom silicon solutions. Marvell's data center segment revenue alone reached $2.17 billion, demonstrating substantial growth. Management indicated that this strength was broad-based, with optical DSPs, scale-out switching, broadband analog, CXL memory expansion, and custom silicon all contributing to momentum and a strengthened outlook.
Looking ahead, Marvell forecasts third-quarter fiscal 2027 revenue between $3.15 billion and $1.05 to $1.15 per share in non-GAAP earnings. The non-GAAP gross margin is expected to range from 57.5% to 58.5%, with non-GAAP operating expenses projected at approximately $655 million. For the full fiscal year 2027, Marvell now anticipates revenue of about $12 billion, up from the previous estimate of $11.5 billion. The company has also raised its fiscal 2028 revenue outlook to approximately $18 billion, with data center revenue projected to grow by over 60% in both fiscal 2027 and 2028.
What Do Analysts Expect For MRVL Stock?
Following the quarterly results, Goldman Sachs reiterated a “Neutral” rating and a price target of $195, suggesting that the stock might trade within a narrow range due to results aligning with expectations. The firm noted that strong performance was largely anticipated by investors, potentially incorporating the positive guidance into the current stock price.
TD Cowen analyst Sean O’Loughlin maintained a “Hold” rating with a $245 price target. In contrast, Oppenheimer analyst Rick Schafer reaffirmed a “Buy” rating, setting a price target of $325.
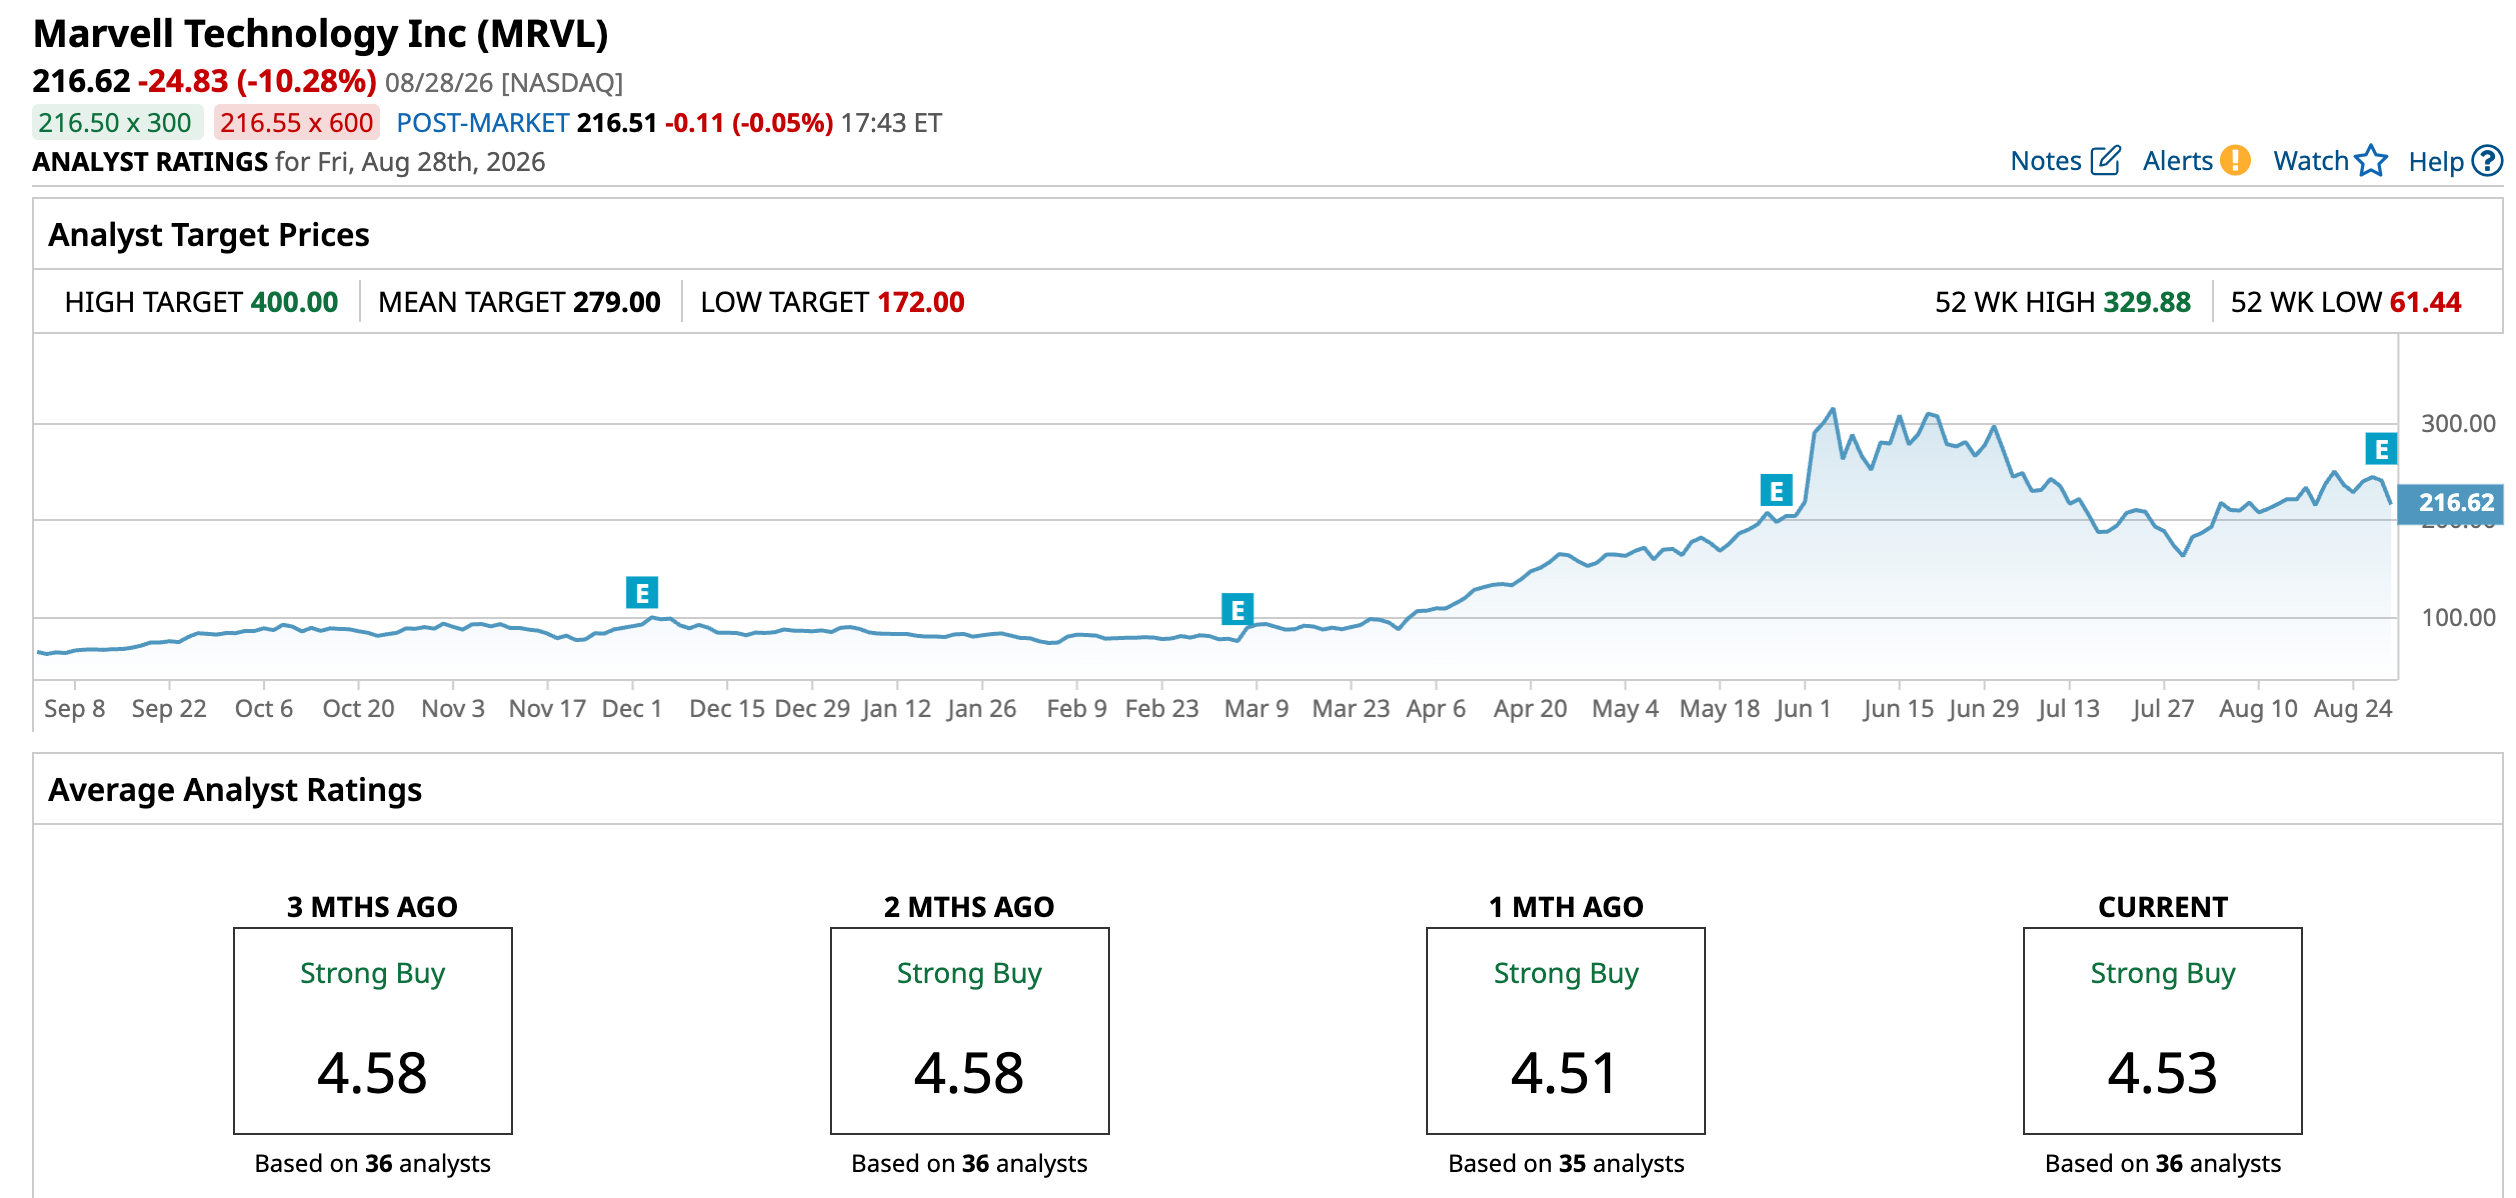
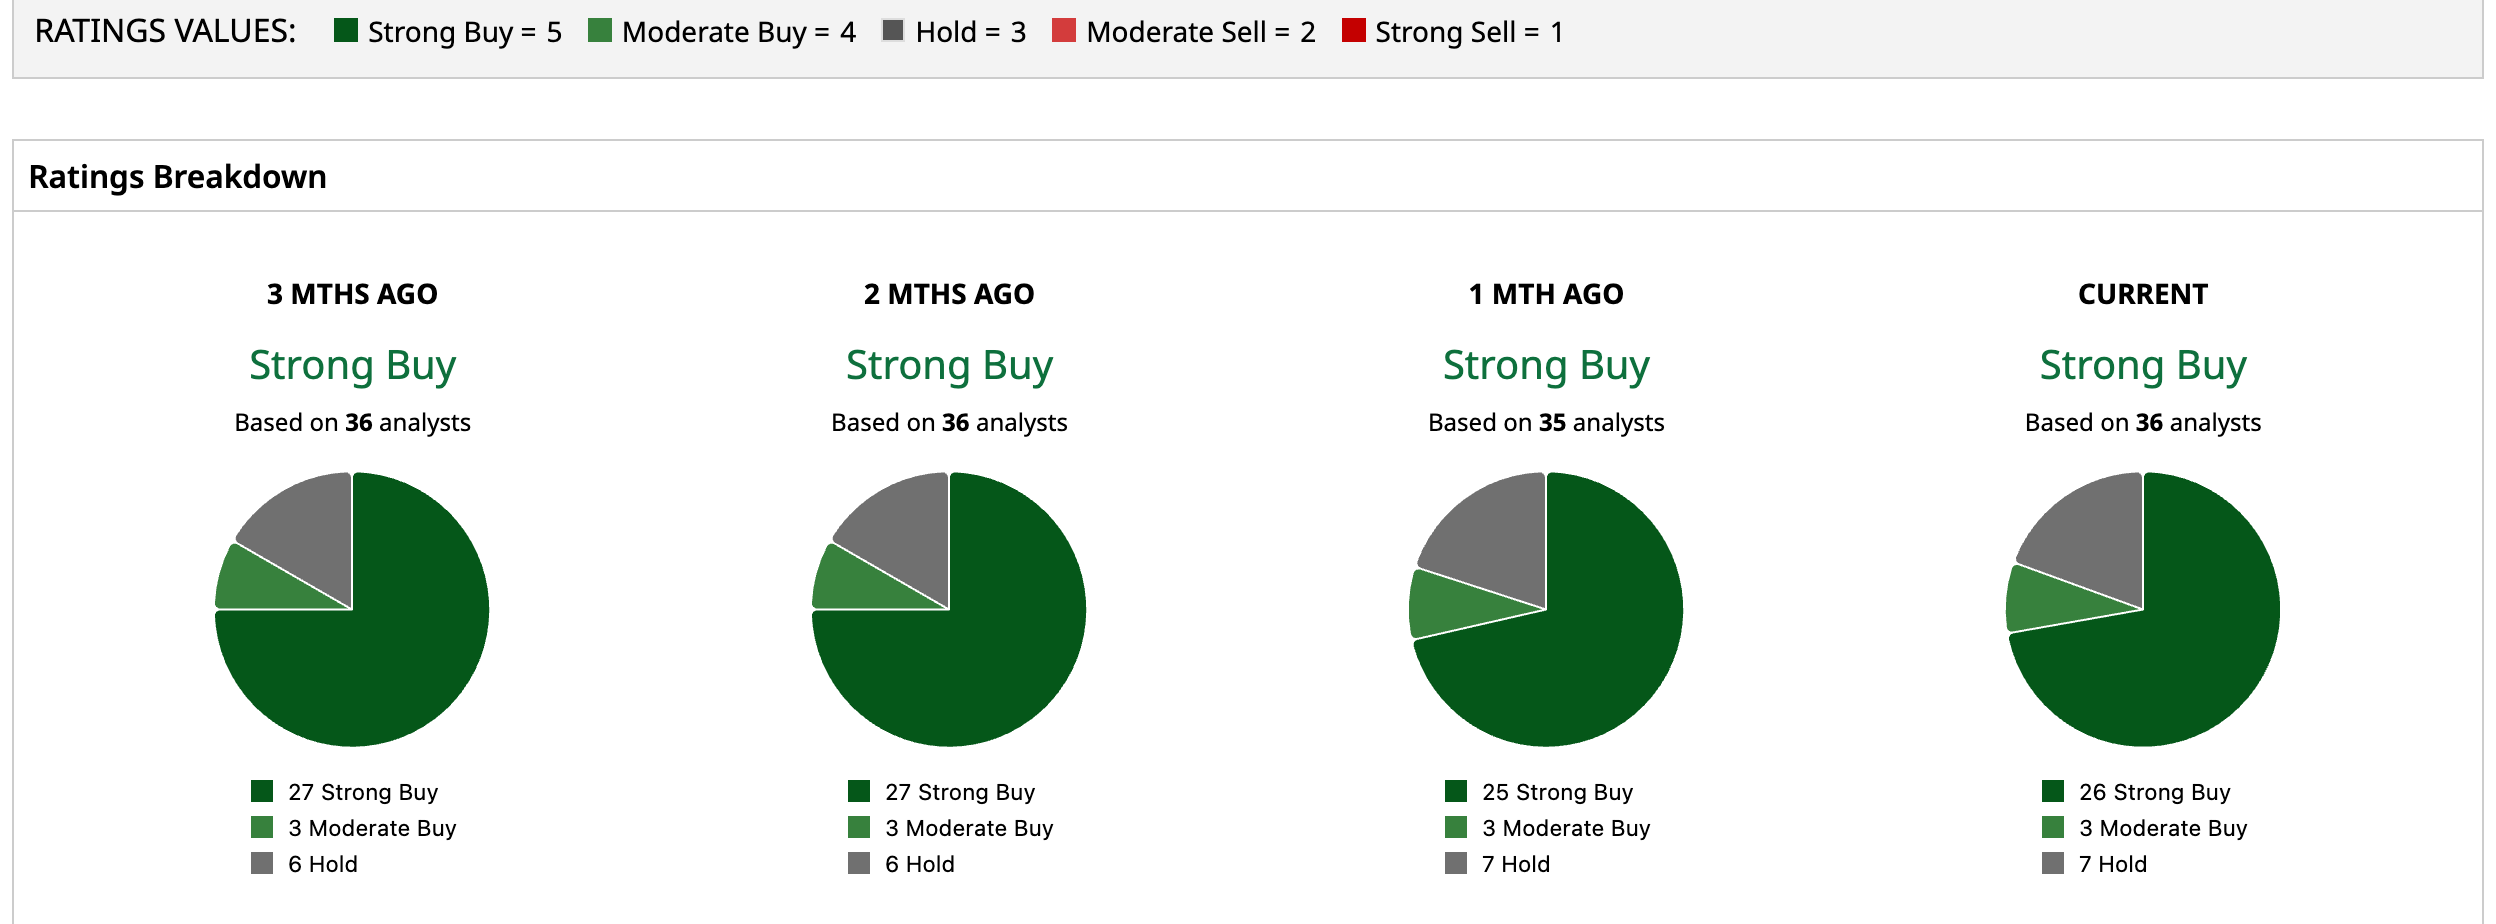
With 36 Wall Street analysts covering the stock, Marvell Technology holds a consensus “Strong Buy” rating. Of these, 26 recommend “Strong Buy,” three suggest “Moderate Buy,” and seven rate it as “Hold.” The median price target of $279 indicates a potential upside of 28.8% from current levels, while the high price target of $400 suggests an upside of 84.7%.