Alphabet (GOOG, GOOGL) is gearing up for its third-quarter earnings report around October 28th, with expectations of a substantial stock rally. The tech giant is uniquely positioned in the burgeoning AI market, boasting robust Google Cloud performance and significant investments in data centers and proprietary AI chips. Despite a recent dip from its peak, analysts and valuation metrics suggest Alphabet’s current price offers an attractive entry point for investors expecting strong returns driven by its AI strategy.
A pivotal moment is fast approaching for investors in tech giant Alphabet (GOOG) (GOOGL): its third-quarter earnings announcement, expected around October 28th. The company appears exceptionally well-positioned for a surge following this report, driven by a strong fundamental setup.
Few companies are better equipped to capitalize on the escalating AI arms race than Alphabet. With the stock currently trading more than 10% below its all-time high, the present moment presents a compelling buying opportunity for discerning investors.
Image source: The Motley Fool.
Alphabet's Strategic AI Investments Under Scrutiny
Artificial intelligence is profoundly reshaping Alphabet's diverse business segments. Its primary revenue generator, advertising across the Google product ecosystem, has seen a subtle but impactful shift as AI is integrated more deeply. Last quarter, Google Search revenue impressively climbed 17% year-over-year, a strong performance for such a mature business unit.
However, much of the market's attention will be focused on the performance of Google Cloud, Alphabet's cloud computing division. Google Cloud delivered spectacular results in Q2, with revenue soaring an astounding 82% year-over-year and its operating margin reaching 36%. Such robust growth is increasingly becoming an expectation. Alphabet plans to invest approximately $200 billion in capital expenditures by 2026, with the vast majority earmarked for data centers to support its AI ambitions.
Investors eagerly anticipate a strong return on these significant investments. If Google Cloud can sustain or even accelerate its growth towards triple-digit rates, these expenditures will be clearly justified. This outcome appears highly probable, supported by additional strategic developments.
Alphabet has also innovated with its own leading AI computing chip, the Tensor Processing Unit (TPU), specifically designed for AI workloads. While initially for internal use, Alphabet is now offering these TPUs to external clients, creating an exciting new revenue stream. The company informed investors that TPU sales will progressively ramp up through the end of 2026, with the majority of the revenue expected to materialize in 2027. The upcoming Oct. 28th earnings call will offer crucial insights into the early trajectory of this new venture.
All these factors collectively suggest that Alphabet is poised to deliver excellent results, a sentiment echoed by Wall Street analysts who project a 25% growth rate for the tech giant—a commendable figure for a company of its scale. This robust outlook, combined with a sensible valuation, positions the stock for a potential rally post-earnings.
Alphabet's Valuation: A Reasonable Entry Point
Unlike many AI-centric stocks that trade at inflated premiums, demanding flawless quarterly performance to maintain their valuations, Alphabet (GOOG, GOOGL) presents a more reasonable price tag. Traditional earnings-per-share (EPS) metrics can be misleading for Alphabet due to significant, unrealized gains from its investments over the past year. This renders the standard price-to-earnings (P/E) ratio less effective for a true valuation.
Instead, a more accurate assessment comes from examining its operating income. From this perspective, Alphabet exhibits a quite reasonable valuation.
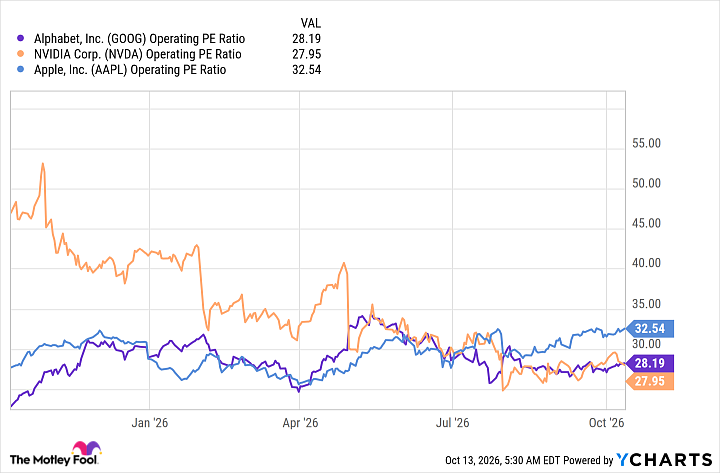
GOOG Operating PE Ratio data by YCharts
Currently valued at 28 times its operating income, Alphabet trades comparably to its trillion-dollar peer group. This valuation is not substantially higher than its average over the past year, indicating that its stock gains are fundamentally driven by its results rather than speculative fervor. If Alphabet delivers another strong quarter, as indications suggest, this could serve as the catalyst for the stock to surpass its previous all-time highs and continue its upward trajectory.
Considering these factors, Alphabet (GOOG, GOOGL) stands out as a compelling stock to consider acquiring right now.