




As the AI revolution drives massive investment in cloud infrastructure, industry giants Amazon, Alphabet, and Microsoft are locked in a fierce battle. While Microsoft’s Azure boasts a strong growth rate, its deceleration compared to accelerating growth at Google Cloud and Amazon Web Services raises a strategic concern. The author recommends Amazon and Alphabet as superior buys due to their accelerating cloud divisions and aggressive market share capture in the burgeoning AI landscape.
Amazon (AMZN), Microsoft (MSFT), and Alphabet (GOOG, GOOGL) are widely recognized as the dominant 'hyperscalers,' operating the leading cloud computing platforms essential for the burgeoning AI build-out. With most companies lacking the computing power to run advanced AI workloads, they increasingly rely on these three giants to rent computing capacity. The demand is so immense that this trio is collectively investing hundreds of billions of dollars in data center capital expenditures this year, a trend expected to continue into 2027. This massive investment promises monstrous growth, but the crucial question remains: are all three solid buys right now?
Among these three tech titans, I identify two as smart investment opportunities, with one standing out as the stock to potentially avoid.
Image source: Getty Images.
One Stands Out with Superior Growth Momentum
These three companies share a common business model: a foundational primary business coupled with a rapidly expanding cloud computing division. Amazon anchors its operations with its vast e-commerce empire, Microsoft thrives on its extensive business software suite, and Alphabet commands the ubiquitous Google Search ecosystem. All three generate substantial cash flows, enabling them to make the heavy upfront investments required for cloud computing infrastructure, which in turn promises immense future cash generation.
When it comes to pure growth rates within their cloud segments, Alphabet's Google Cloud is currently the standout performer. In Q2, Google Cloud reported an impressive 82% year-over-year revenue increase. What's more, this growth is highly profitable, with its operating margin soaring from 21% to 36% over the year. These results are exceptional, and Google Cloud's growth isn't just fast; it's accelerating, having posted a 63% growth rate in Q1. As more computing capacity comes online, it wouldn't be surprising to see this growth rate potentially cross into triple digits in the coming quarters.

NASDAQ: GOOGL
Key Data Points
Amazon Web Services (AWS) and Microsoft Azure are closer in their growth trajectories, but a key detail in Microsoft's recent results gives pause. In Q2, AWS grew 37%, while Azure grew 43%. However, looking back at Q1, AWS's growth rate was 28% compared to Azure's 40%. The significant point here is that AWS's growth is rapidly accelerating—mirroring Google Cloud's impressive trend—whereas Azure's growth rate appears to be stagnating around 40%.

NASDAQ: MSFT
Key Data Points
While this could merely be a one-off quarterly anomaly for Microsoft, and a return to rapidly accelerating Azure revenue next quarter could alleviate concerns, a sustained 40% growth rate while its primary competitors experience accelerating expansion could signal a significant red flag. It might suggest Microsoft is not fully capitalizing on the immense market opportunity presented by the current technological arms race in AI.
Consequently, I favor Amazon and Alphabet over Microsoft at this juncture. But does valuation play a role in this decision?
Valuation: A Complex Calculation
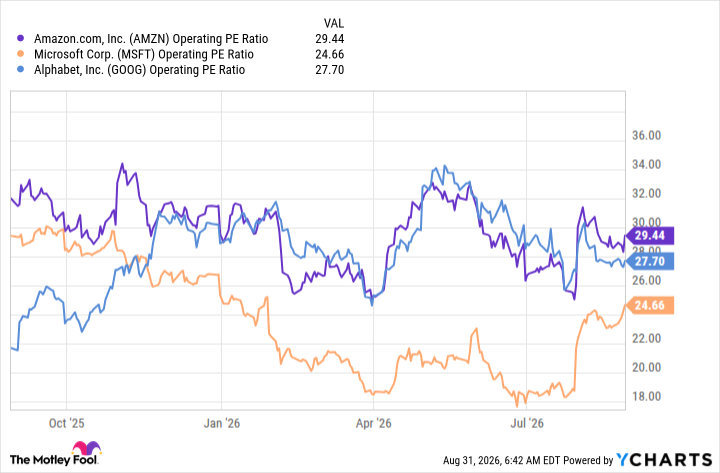
Valuing these companies isn't straightforward. Each has invested billions into emerging AI firms, which tends to distort traditional earnings-per-share (EPS) and price-to-earnings (P/E) ratios. Therefore, evaluating these stocks based on operating income offers a clearer perspective.
AMZN Operating PE Ratio data by YCharts
From an operating income standpoint, Microsoft appears to be the most attractively priced. This valuation might reflect the market's adjustment for the observed discrepancy in Azure's growth trajectory compared to its cloud computing peers, potentially pricing in the rapid acceleration seen at AWS and Google Cloud.
Despite Microsoft's seemingly cheaper price tag, I continue to favor Amazon and Alphabet. Their accelerating growth rates and aggressive market share capture in the booming AI industry present a more compelling long-term investment setup than a lower valuation now. This makes them my top AI stocks to acquire and hold as the AI arms race intensifies over the coming years.














