


Broadcom (AVGO) stock has seen a significant decline over the past year, but analysts maintain a strong ‘Buy’ sentiment with a mean price target suggesting considerable upside. Despite recent market volatility and competitive pressures, the company’s AI chip sales and long-term growth projections remain robust.
The upcoming fiscal Q4 earnings report is a key event to watch, with investors focused on AI revenue figures and capital allocation decisions. The stock currently trades at attractive multiples, leading many to believe it may be undervalued.
Broadcom Stock's Plunge: A Deep Dive into AVGO's Value Amidst Market Volatility
Key Takeaways
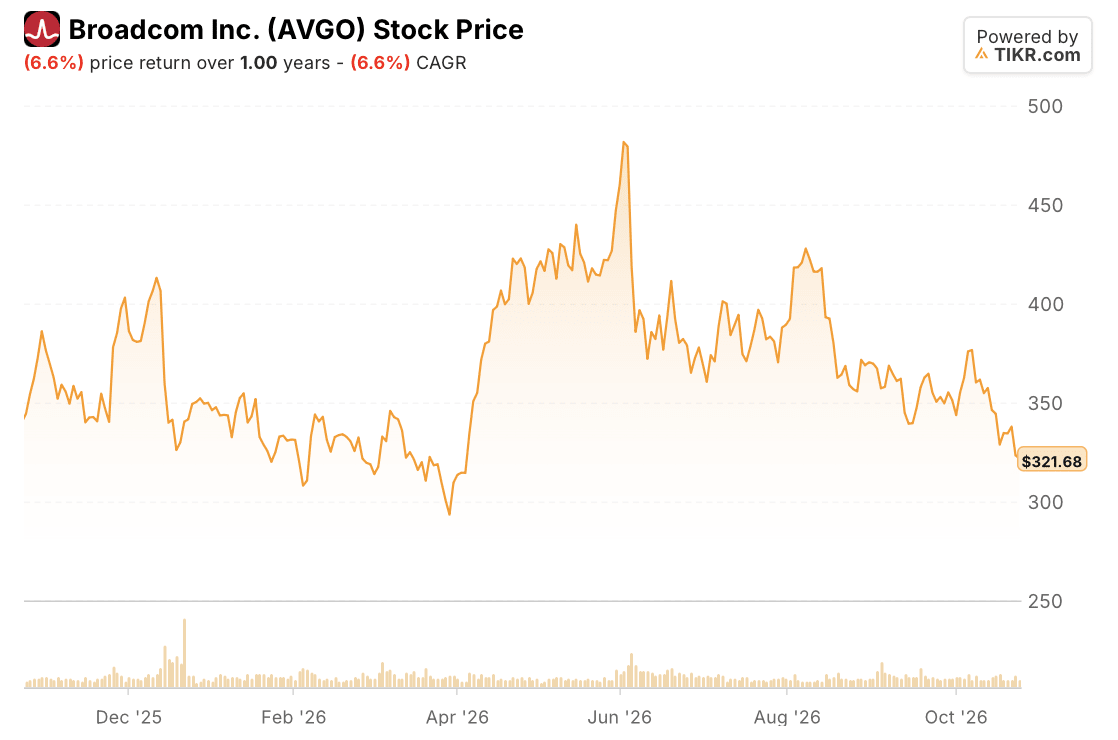
- Broadcom (AVGO) stock has experienced a 6.6% decline over the past year, currently trading at $321.68, significantly down from its June peak.
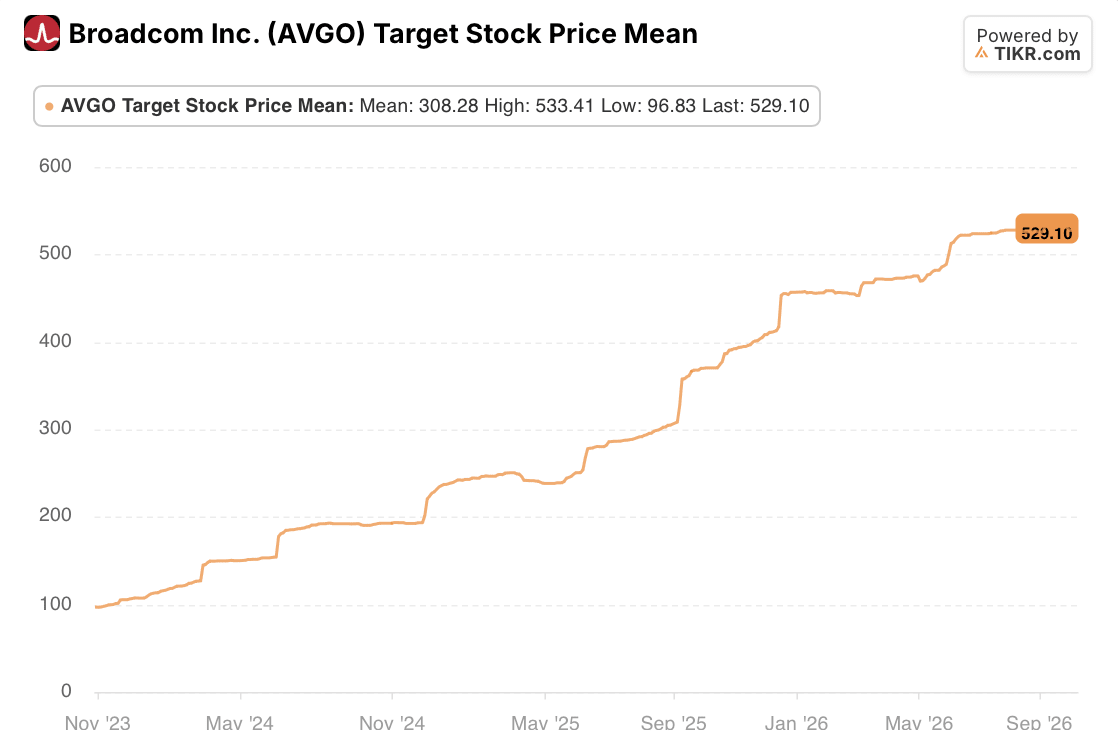
- Analysts remain bullish, with a mean price target of $529.10, indicating substantial upside potential.
- Projections show normalized Earnings Per Share (EPS) poised for significant growth, aligning with the CEO's optimistic outlook.
- Upcoming fiscal Q4 earnings report is crucial, with AI chip sales a key focus against ambitious guidance.
Broadcom (AVGO) stock has navigated a turbulent year, shedding 6.6% of its value to close at $321.68 on October 23rd. This downturn erases much of the spring rally, which was fueled by a significant long-term chip deal with Google. Despite raising its AI revenue outlook and projecting a doubling of AI chip sales for the next two fiscal years, the stock's trajectory has moved in the opposite direction of its underlying business performance.
The Road to $479 and Beyond
The year began with headwinds for Broadcom. A late 2025 warning about the impact of lower-margin custom AI processors on profitability led to an 11% drop in December. The stock continued its descent, dipping below $300 by early April.
A pivotal moment arrived on April 6th with the disclosure of a long-term agreement with Google. This deal involves the development and supply of future generations of Google's Tensor Processing Units (TPUs) and networking components for AI racks, extending through 2031. The agreement also includes Anthropic's access to substantial TPU-based compute power starting in 2027. This news propelled Broadcom's stock to a June 3rd closing price of $479.23.
Setbacks Derail the Spring Rally
However, the second-quarter report released on the same evening as the Google deal's peak valuation proved to be a turning point. Revenue of $22.19 billion slightly missed analyst expectations, and crucially, the company maintained its AI chip forecast instead of raising it. This disappointment triggered a sharp 12.59% drop on June 4th, erasing $60.32 per share in a single trading session.
Further pressure mounted with news from a competitor. On August 19th, Marvell Technology (MRVL) announced its own custom chip agreement with Google, including a warrant for Marvell shares. This development, signaling a second supplier for Google's TPUs after Broadcom's decade-long exclusive relationship, led to another approximately 5% decline in Broadcom's stock.
TIKR Tracks 53 Analysts on Broadcom. How Many Say “Buy”?
Explore detailed Buy, Hold, and Sell ratings for Broadcom, alongside Wall Street's revenue and earnings estimates, all conveniently located on TIKR. Join over 500,000 investors researching stocks like Broadcom. See Broadcom’s Analyst Ratings
A Record Quarter Couldn't Sustain the Rally
Broadcom's fiscal third-quarter report, released on September 2nd, showcased remarkable growth. Revenue surged 86% year-over-year to $29.6 billion, with AI semiconductor revenue more than tripling to $16.7 billion. Adjusted EPS of $3.32 surpassed estimates of $3.24.
The company also raised its fiscal 2026 AI revenue outlook to $58 billion from $56 billion, projecting a doubling of AI sales to $115 billion in fiscal 2027, and another doubling to $230 billion in fiscal 2028. Despite these impressive figures, the fourth-quarter revenue guidance of $34.8 billion fell slightly short of the consensus estimate, and the stock experienced a nearly 3% dip the following day.
CEO Hock Tan reiterated the company's strong financial trajectory on the Q3 fiscal 2026 earnings call, stating, "We are very much on target to exceed $30 in earnings per share in fiscal 2028."

Analyst estimates align with Tan's forecast, with normalized EPS projected to rise from $11.66 in fiscal 2026 to $30.38 in fiscal 2028, a substantial increase from $6.82 in fiscal 2025.
October's Chip Sell-off Pushes AVGO Lower
On October 12th, CEO Hock Tan commented on the AI investment landscape, comparing many AI investors to "casino gamblers" and highlighting capital as the primary constraint on AI growth, rather than chip supply. Broadcom shares saw a modest gain the following day.
However, the broader market downturn, particularly in the semiconductor sector, had a more significant impact. The Philadelphia Semiconductor Index plunged 11.4% in the week ending October 16th, the largest weekly drop since March 2025. Concerns over inflation, potential Federal Reserve rate hikes, and debt issues among AI infrastructure providers like CoreWeave, created a ripple effect across AI-related stocks. Broadcom closed up 1.78% on October 19th but subsequently declined to $321.68 by October 23rd.
Why Wall Street Remains Confident in Broadcom
Despite the stock's recent performance, the analyst community maintains a strongly optimistic outlook. The mean price target stands at $529.10, representing a 64.5% upside from the October 23rd closing price. This target has steadily increased throughout 2026, even as the stock price decreased.
Analysts appear to be anchoring their valuations on the company's robust order book and long-term growth prospects, particularly in AI. The recent market volatility in the chip sector has not significantly altered their fundamental assessments.
What Broadcom Needs in Its December Report
At its current trading price, Broadcom's stock appears undervalued, trading at approximately 16.6 times the Street's fiscal 2027 EPS and 10.6 times its fiscal 2028 EPS. This valuation is notably low for a company projecting such aggressive AI revenue growth.
The upcoming fiscal fourth-quarter report, slated for release on December 9th, is critical. Broadcom has guided for $34.8 billion in revenue, with $21.7 billion from AI chips and an operating margin near 66%. The company's commitment to not updating long-term AI targets quarterly means this specific AI revenue figure will be closely scrutinized to confirm the company's growth trajectory.
Furthermore, the December capital allocation decision by the board is highly anticipated. At a Goldman Sachs conference, CEO Hock Tan indicated that a stock buyback is a likely use of capital.
Valuing Broadcom: Your Turn
TIKR provides a free tool to forecast the future price of any stock. By inputting a few assumptions into TIKR’s valuation model, you can explore potential future values for AVGO stock, starting with Wall Street consensus estimates or customizing inputs based on your own market analysis. Value Broadcom Inc. for free→
Disclaimer: The content provided on TIKR is for informational purposes only and does not constitute investment or financial advice. TIKR and its content team create analyses based on data from the TIKR Terminal and analyst estimates, which may not encompass all recent company news or updates. TIKR holds no positions in the stocks mentioned. Happy investing!






