




Amazon and Alphabet are investing a combined $420 billion in data center expansion through 2026 to meet surging demand for cloud computing and AI services. While this massive capital expenditure is driven by rapid revenue growth in their cloud divisions, it raises questions about shareholder returns. Despite premium valuations, their strong growth and reasonable forward P/E ratios suggest they remain compelling investment opportunities poised to outperform the market.
Amazon (AMZN -1.78%) and Alphabet (GOOG -2.09%) (GOOGL -2.28%) are making colossal investments in the data center space, collectively planning to spend approximately $420 billion by 2026. Amazon projects spending around $220 billion, while Alphabet forecasts between $195 billion and $205 billion, though this figure could rise given their consistent upward revisions. This massive capital expenditure grants them nearly unlimited capacity to ramp up computing power. However, it raises the question: could this enormous sum be better utilized elsewhere, such as returning value directly to shareholders?
Image source: Getty Images.
Cloud Computing: A Booming Business Driving Investment
Both Amazon's AWS and Alphabet's Google Cloud are experiencing significant demand, necessitating substantial infrastructure investments. Cloud computing, at its core, operates like a rental business: high demand requires increased capacity, which comes at a significant cost. However, these investments are designed to yield substantial returns over time, often many times the initial outlay.
This principle underpins Amazon and Alphabet's aggressive spending on AI data centers, a strategy that appears to be paying off handsomely.

Today's Change: -1.78% $-4.57
Current Price: $252.40
Market Cap: $2.7T
52wk Range: $196.00 - $287.20
Volume: 33.1M
During the second quarter, Amazon Web Services (AWS) reported revenue growth of 37% year over year, its strongest performance in nearly five years. CEO Andy Jassy highlighted that current computing capacity is insufficient to meet projected demand for 2026 and likely extending into 2027, with significant demand already visible for 2028. This robust demand clearly justifies Amazon's substantial capital expenditures.

Today's Change: -2.28% $-7.71
Current Price: $330.65
Market Cap: $4.0T
52wk Range: $235.84 - $408.61
Volume: 33.2M
Alphabet's Google Cloud is exhibiting even more impressive growth, with revenue soaring 82% year over year. While smaller than AWS ($24.8 billion in Q2 vs. AWS' $42.2 billion), its smaller base allows for faster percentage growth. A significant driver for Alphabet is the anticipated strong sales of its custom AI chips, which offer superior performance at a lower cost compared to traditional GPUs for optimized workloads. These sales are expected to further accelerate Alphabet's growth, potentially pushing it towards triple-digit growth rates.
Valuation: Are Amazon and Alphabet Still Good Buys?
Both companies are experiencing rapid growth, which validates their significant investments. However, the question remains whether these stocks are still attractive investments.
While neither Amazon nor Alphabet can be considered cheap, the market rarely offers top-tier companies at a discount. Their projected growth over the next year supports their current valuations. Using 2027 earnings projections, Amazon trades at a forward P/E ratio of approximately 25, and Alphabet at about 23. This suggests that about a year of growth is priced into their current stock values, which is reasonable given their impressive growth trajectories.
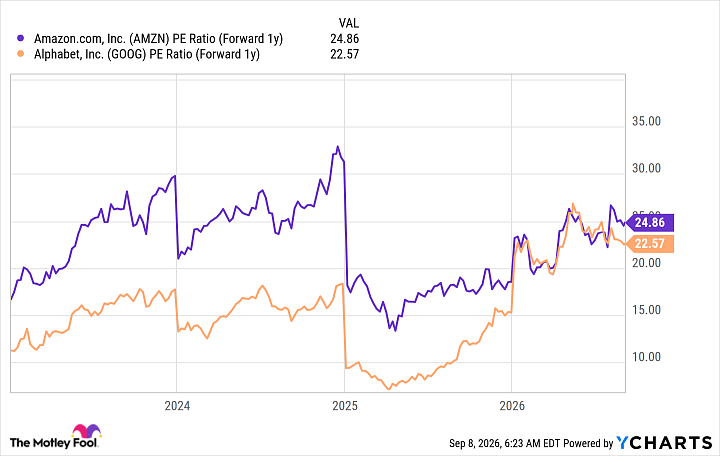
AMZN PE Ratio (Forward 1y) data by YCharts.
Although they may not be the market's absolute best performers in the long run, Amazon and Alphabet are poised to significantly outperform the broader market, making them strong investment choices at present.






